

Cash Advance Now - PayDaySay

- 774.00 Reviews
- 4.6
- Downloads
- 100,000+
Our take on Cash Advance Now - PayDaySay from Appgk
When I look at a cash-advance app, I do not judge it by the promise of speed alone. I want to know what happens when I am away from home, working from a phone, dealing with a weak signal, or trying to make a decision before an urgent bill becomes a bigger problem. Cash Advance Now - PayDaySay is built for that narrow moment: someone needs a small amount of money quickly and wants to begin the process from a mobile device rather than visit a branch.
My overall impression is that it is best understood as a convenient starting point for a short-term borrowing request, not as a replacement for a bank account, budgeting tool, or long-term credit solution. The app is free to install, belongs to the finance category, and comes from PayDaySay. Its audience is broad because the content rating is Everyone, but the financial decision itself still deserves adult judgment. A simple interface can make borrowing feel easy; it cannot make repayment easy if the timing is wrong.
What the app is really useful for
The central use case is straightforward. You open the app when an unexpected expense arrives and want to explore an instant payday cash advance from your phone. That could mean dealing with a gap before a regular payday, covering a necessary purchase, or checking whether a short-term option is available without making a trip. I found the value less in “having money on demand” and more in being able to begin the request during the exact moment the need appears.
That distinction matters. Cash Advance Now - PayDaySay is not a promise that every request will produce the amount you want, and it should not be treated as free money simply because the application itself costs nothing. The app is free to download, while any borrowing decision should be evaluated separately, including the repayment terms, total cost, due date, and consequences of missing that date. I would read every offer carefully before accepting anything.
Best Parts of Cash Advance Now - PayDaySay
Things to Keep in Mind About Cash Advance Now - PayDaySay
The store summary focuses on borrowing an extra two hundred dollars instantly, but I would not let that headline become my personal budget. A useful habit is to decide the maximum repayment amount before opening the app. If you cannot explain where the repayment will come from, the convenience of applying on a phone is not a sufficient reason to proceed.
Where connectivity changes the experience
This is an online financial workflow, so connectivity is part of the experience rather than a minor technical detail. You need a working connection to open the service reliably, move through an application, and receive current responses. A weak mobile signal can turn a quick request into a sequence of loading delays, and that is particularly frustrating when you are standing in a shop, sitting in a car, or trying to resolve a bill before a deadline.
News and Features Related to Cash Advance Now - PayDaySay

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I recommend starting the process from a stable Wi-Fi connection when possible. That does not make the financial decision safer by itself, but it reduces the chance of a page failing halfway through or a submission being interrupted. If you must use mobile data, wait until the signal is steady and avoid switching between Wi-Fi and cellular service while entering information.
There is also a practical privacy angle. Public Wi-Fi may be convenient, but a borrowing request involves sensitive personal and financial details. I would rather use a trusted home network or a secure mobile connection than fill out an application on an open network in a café or airport. The app’s convenience is strongest when paired with a private, dependable connection.
Don't want to read the full review?
Another small but important point is timing. Do not begin an application while rushing between appointments if you cannot finish it carefully. Connectivity problems are easier to handle when you have enough time to check each screen, notice whether a submission completed, and save any confirmation details shown by the app. Speed is useful only when it does not encourage careless answers.
Using it in real mobile situations
The most believable scenario for this app is a short-notice expense that appears during an ordinary day. Imagine discovering that a necessary payment is due before your next paycheck. You are away from your computer, have your phone with you, and want to see whether a cash advance route is available. PayDaySay fits that first step because it lets you investigate from the device already in your hand.
Screenshots
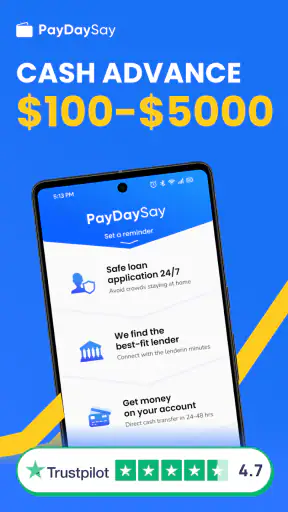
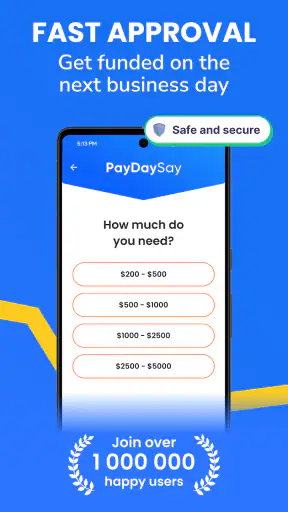
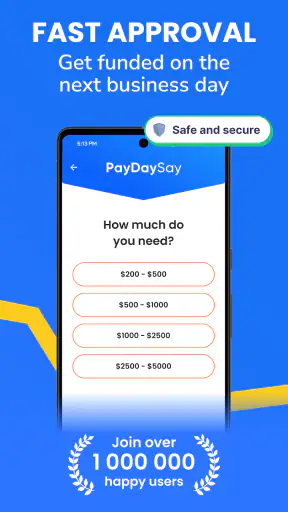
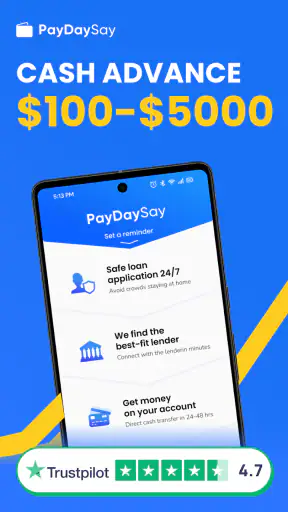
In that situation, I would not apply while distracted. I would move somewhere private, confirm the connection, check the amount I actually need, and review the repayment information before accepting any offer. If the app presents several stages, I would take a screenshot or note the important details only if doing so is appropriate and secure. The goal is to avoid relying on memory after closing the screen.
The mobile format is also useful for comparing the app with more traditional alternatives. A bank branch may require travel and business-hour availability. Calling a lender may involve waiting or explaining the same information verbally. A credit card can be faster for an existing cardholder, but it may not be suitable for someone who does not have available credit or wants to avoid adding a purchase to a revolving balance. A borrowing app can feel more immediate, but its speed should be balanced against the cost and repayment structure.
That comparison is where I would place PayDaySay. It is potentially more convenient than a branch visit for a small, urgent request, yet it is not automatically better than using savings, asking a trusted person, negotiating a bill extension, or checking an existing bank product. Those alternatives may be slower, less comfortable, or unavailable, but they can sometimes carry less financial risk. The right choice depends on the expense and the repayment plan, not on how quickly the first screen opens.
What to check before submitting anything
My strongest practical advice is to separate the application process from the acceptance decision. First, determine whether the service can help with your situation. Then pause and inspect the actual offer. Look for the amount you would receive, the amount you would repay, the date repayment is expected, and any charges or conditions shown in the agreement. If any part is unclear, do not assume that “instant” means simple or inexpensive.
I would also avoid requesting more than the expense requires. A larger amount can make the immediate problem feel solved while creating a tighter next payday. Borrowing only what is necessary gives you a better chance of keeping the repayment manageable. This is an especially important discipline with a phone-based service because the reduced friction can make an extra amount feel harmless.
Another useful check is to compare the proposed repayment with your complete upcoming budget, not just your next expected income. Include rent, utilities, food, transport, existing debt payments, and any automatic withdrawals. If repayment would force you to borrow again for essentials, the app is not solving the problem; it is moving it forward.
Because PayDaySay is a finance app rather than a general money manager, I would keep my own record of what I accept. Note the date, amount, repayment date, and total obligation in a secure place. That habit is valuable if you use more than one financial service, because a phone notification or email can be missed while a personal calendar reminder gives you another line of defense.
When a connection fails or the process feels uncertain
Connectivity problems deserve special attention in a borrowing workflow. If a page stops loading, do not repeatedly tap the submission button. First check whether the request appears to have gone through, whether you received a confirmation, or whether the app has returned to an earlier step. Repeated submissions could create confusion, especially if the first attempt actually reached the service before the screen froze.
If the app closes unexpectedly, reopen it only after your connection is stable. Review the current screen carefully instead of assuming that you need to start over. If the process asks for information again, compare the details with what you entered previously. A calm recheck is safer than rushing because you are worried about losing the opportunity.
I would also avoid beginning a request when the phone battery is nearly empty. This sounds obvious, but a dead phone at the final stage can leave you unsure whether the application was completed. Keep the device charged enough to finish the process and retain any confirmation information. The app may be designed for mobile convenience, but the surrounding conditions still affect whether that convenience works in practice.
Do not treat an error message as a reason to keep experimenting with personal information. If something fails repeatedly, stop, record the wording of the error if possible, and use the app’s available support route when you can do so safely. A failed connection is inconvenient; an incorrectly repeated financial submission is more serious.
This is also why I would not rely on the service for an expense that must be paid within minutes. Even a well-designed app depends on the phone, the network, the application flow, and the response from the financial service. For a genuinely immediate emergency, have a backup plan rather than assuming a mobile request will always finish instantly.
Keeping mobile data and personal information under control
For most people, the amount of data used by a finance app is less important than the sensitivity of the information entered. Still, a data-conscious approach makes sense. Use the latest stable connection available, avoid unnecessary repeated reloads, and close the app when you have finished rather than leaving the process open while moving between networks.
I would not complete a borrowing request on a shared device. If you have to use someone else’s phone, it is better to reconsider the timing than risk leaving personal information in autofill fields, browser history, screenshots, or notifications. On your own phone, use the device’s normal security protections and be careful about showing the screen in public.
Notifications deserve a quick review as well. A message that reveals a financial application or repayment detail can appear on a locked screen. Adjust your phone’s notification display if you share living space or frequently place the device on a desk where others can see it. This is not a special feature of PayDaySay; it is a sensible precaution whenever a finance app is used in public or around other people.
I also recommend checking the app identity before entering anything sensitive. The developer listed for this app is PayDaySay, and the current version is 1.26. Keeping the installed app up to date through the official app marketplace is a basic way to reduce confusion between a genuine application and an imitation. Do not install a similarly named file from an unknown source just because the original app is temporarily difficult to reach.
The minimum operating system is Android 6.0, which makes the app accessible to many older Android phones. That broad compatibility is helpful if you do not own a new device, although older hardware may handle modern screens less smoothly. Before applying, make sure the phone has enough battery, storage, and a reliable connection so that an otherwise suitable device does not become the weak point in the process.
Who will get the most from it
I see the strongest fit for someone who understands the exact size and timing of a short-term cash gap, has a realistic repayment source, and values starting the process from a phone. It may also suit people who cannot easily reach a branch or who want to investigate an option outside normal office hours. The app’s mobile format is the main practical advantage.
It is less suitable for anyone looking for a long-term way to manage recurring expenses. If you need help every pay period, a budget review, debt counseling, a lower-cost installment product, or a conversation with your bank may be more appropriate. A payday-style advance can be useful as a one-off bridge, but repeated reliance can turn a temporary gap into a cycle.
I would also skip it if you are unsure about the repayment date, already have several obligations due at the same time, or are considering borrowing for a nonessential purchase simply because the application feels easy. In those cases, the usual alternatives deserve attention first. Waiting, reducing the purchase, negotiating a payment date, or using existing savings may be uncomfortable, but discomfort is not the same as financial harm.
The app has a 4.6 average from around sixteen thousand ratings, with over a hundred thousand installs, so it has clearly attracted substantial attention among people looking for this kind of service. Those figures tell me that the product is familiar to a meaningful audience, but they do not replace my own review of a specific offer. A high average rating cannot reveal whether the amount, cost, or repayment schedule fits your circumstances.
How it compares with familiar alternatives
Compared with a bank branch, PayDaySay is more convenient for a phone-first request and avoids a physical visit. Compared with a phone call, it gives you more control over when you begin and lets you review information on screen. Compared with a credit card, it may appeal to someone who does not want to use an existing card balance, although the actual cost and terms must be compared rather than assumed.
Compared with borrowing from savings, the app is usually the more complicated choice because it creates a repayment obligation. Savings can be emotionally difficult to use, but there is no new lender relationship or future due date attached to money you already own. Compared with asking family or friends, an app may feel more private, while a personal loan may sometimes offer more flexible conversation around timing. Each alternative has a different kind of cost: money, time, privacy, or social discomfort.
That is why I would not call PayDaySay the best finance app for everyone. Its value is concentrated in a specific problem: a small, short-term gap where mobile access matters and repayment is genuinely planned. If your need is larger, ongoing, or uncertain, a conventional loan comparison or professional financial guidance may be a better direction than a quick advance.
My connectivity verdict
After looking at the app through the situations that matter most, I think Cash Advance Now - PayDaySay is a practical option to investigate when a short-term need appears and you have a dependable connection, a private place to use your phone, and a clear repayment plan. Its free installation, accessible Android requirement, and mobile-first purpose make it easy to consider without a branch visit.
The important limitation is that connectivity and convenience can make a serious financial decision feel lighter than it is. A weak signal can interrupt the process, while a strong signal can make it too easy to apply without checking the consequences. I would use the app slowly enough to verify each stage, avoid repeated submissions after an error, and keep my own record of any accepted obligation.
My recommendation is therefore conditional rather than automatic: try it when the expense is genuinely necessary, the amount is limited, and repayment is already mapped out. Skip it when you are using it to cover a recurring shortfall or when the terms do not make complete sense. For the right mobile situation, PayDaySay can be a convenient doorway to a cash-advance request; it should never be mistaken for a substitute for a sustainable financial plan.
Cash Advance Now - PayDaySay FAQ
What is Cash Advance Now - PayDaySay?
Cash Advance Now - PayDaySay is a financial service app designed to help users explore short-term cash advance options and connect with potential lending providers. After entering personal and financial information, users may receive offers based on eligibility. It is important to understand that the app may not be the lender itself, and approval, loan amounts, repayment terms, and interest rates can vary by provider.
How much money can I borrow through PayDaySay?
The amount available through Cash Advance Now - PayDaySay depends on several factors, including your income, employment details, banking history, credit profile, and the requirements of the lender that receives your request. There is no guaranteed advance amount for every applicant. Before accepting an offer, carefully review the total repayment cost, fees, payment schedule, and any applicable annual percentage rate.
Does using PayDaySay guarantee approval or instant cash?
No. Submitting an application through Cash Advance Now - PayDaySay does not guarantee approval, a specific loan amount, or immediate access to funds. Decisions are made according to the criteria of participating providers, and additional verification may be required. Even when an application is accepted, the time required for funds to arrive can depend on the lender, your bank, weekends, and processing schedules.
What information does the app request, and is it safe to provide?
A cash advance application may request information such as your name, contact details, employment status, income, bank account information, and identification details. Only enter data through the official app or a verified website, and check the privacy policy before continuing. Avoid sharing passwords or security codes, and make sure you understand how your information may be shared with lending or marketing partners.
What should I check before accepting a cash advance offer?
Before accepting an offer connected through Cash Advance Now - PayDaySay, review the lender’s identity, repayment date, finance charges, interest rate or APR, late-payment penalties, automatic withdrawal terms, and cancellation policy. Short-term advances can be expensive if repayment is delayed or renewed. Confirm that the payment fits your budget, and consider alternatives such as a bank, credit union, employer advance, or local assistance program.











